Leave a Message

Thank you for your message. We will be in touch with you shortly.

A section headline goes here

Duis aute irure dolor in reprehenderit in voluptate

100%

Vehicula ipsum a arcu cursus mi bibendum neque egestas congue

$40M

Vehicula ipsum a arcu cursus mi bibendum neque egestas congue9

12.000

Vehicula ipsum a arcu cursus mi bibendum neque egestas congue

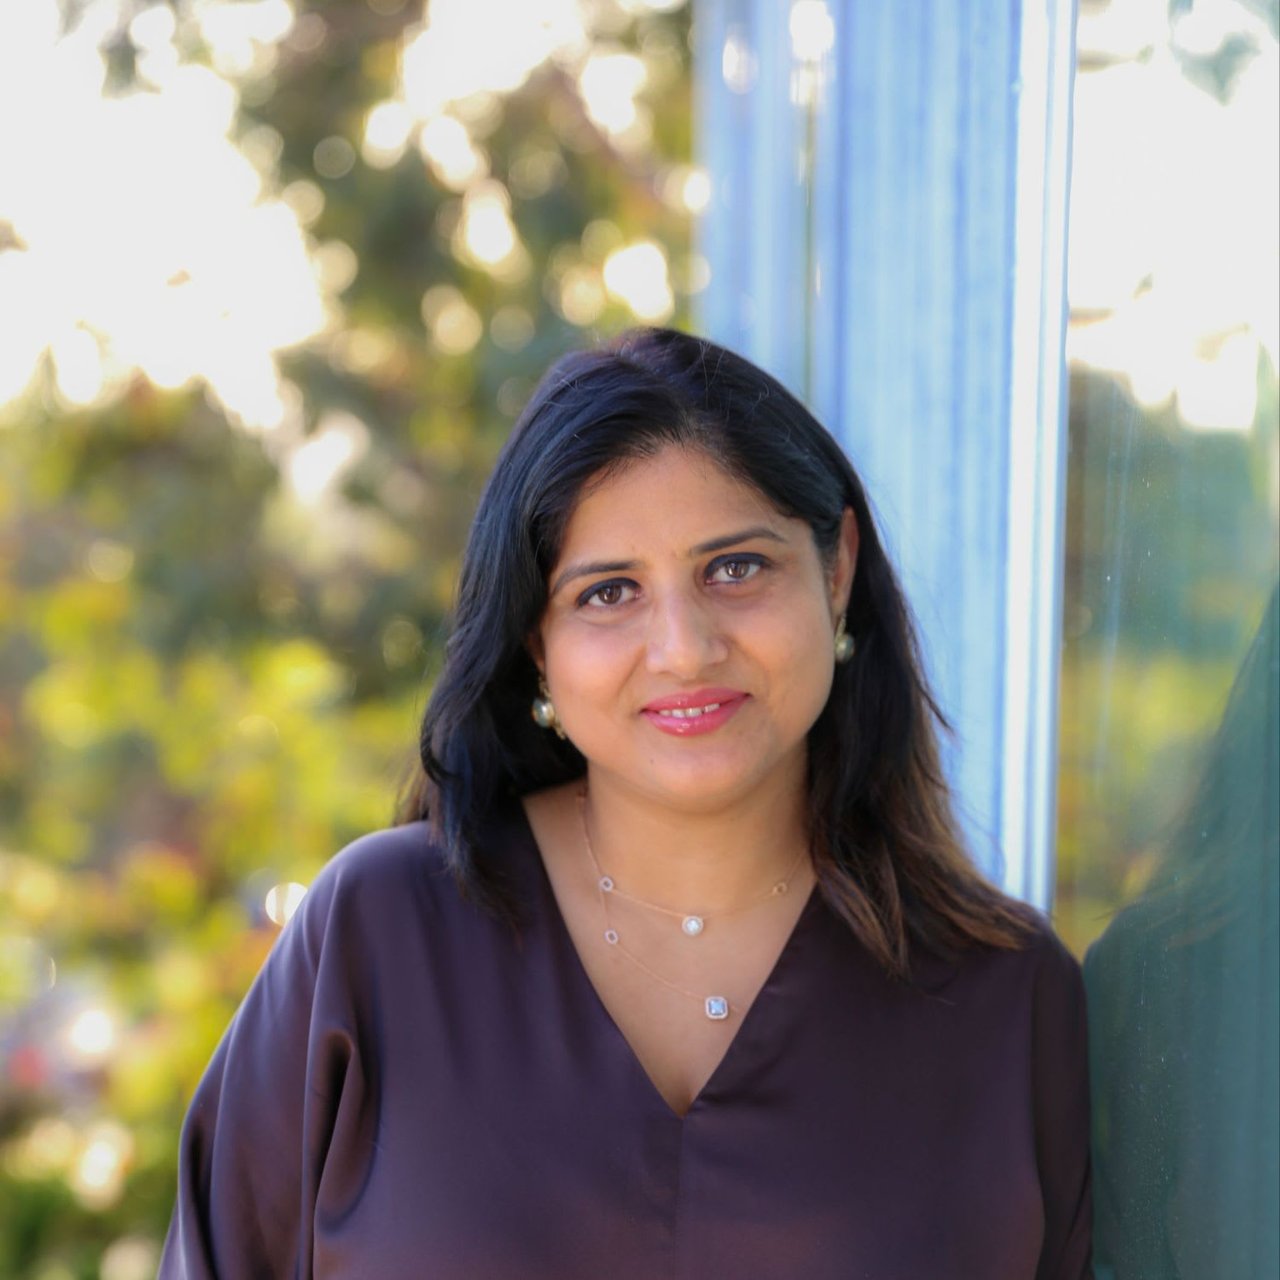
Meet {Agent Name}

Meet {Agent Name}

As the top producing agent in her area, her bespoke approach to buying and selling has been lauded by many in the industry. Her industry specialities include luxury homes, relocations, estate sales and investment properties.

With 16 years of experience in the real estate industry, she has been through multiple market cycles as an agent, buyer and investor, and has a deep understanding for the often-complicated process that her clients will encounter.

WHAT OUR CLIENTS SAY

I recently purchased my home in Palo Alto with invaluable guidance from Noopur. Throughout the entire process—bidding, buying, financing—she stood by us like a pillar, offering expert advice at every step. Her local knowledge about the area, strategic insights about how to think from an investment angle and creative financing approach made it possible. Without her support, we wouldn’t be in our dream hom...
— Ravi Benwal

WHAT OUR CLIENTS SAY

We recently closed on an investment property, and we couldn’t be more grateful to have worked with Noopur. From day one, she demonstrated exceptional trustworthiness, responsiveness, and professionalism. She was a true partner in our investment journey. She took the time to understand our financial goals and provided strategic insights on location selection, rental potential, and long-term appreciation. ...

— 6/8/2025 - asj ankit | Bought a home in 2025.

WHAT OUR CLIENTS SAY

I cannot say enough about Noopur’s dedication, expertise, tireless work, attention to detail, and overall professionalism. She was so thorough on everything from market research to recommendations related to contractors, stagers, and title company. The effort she put into orchestrating all the people, communication, and moving parts was no small fete. She stayed focused and navigated the end to end proce...

— 6/12/2025 - atkins kerri | Sold a Single Family home in 2025 in Menlo oaks, Menlo park, CA.

How much is your Santa Monica home worth?

  • Instant property valuation
  • Expert advice
  • Sell for more

Our Blog

Stay up to date on the latest trends in real estate.

Two Moves That Can Get You Into Your First Home Sooner

October 7, 2026

For a lot of first-time buyers, owning a home can feel perpetually a few years out of reach. Saving for a down payment takes time, and each year you spend renting can … Read more

Two Moves That Can Get You Into Your First Home Sooner

October 6, 2026

For a lot of first-time buyers, owning a home can feel perpetually a few years out of reach. Saving for a down payment takes time, and each year you spend renting can … Read more

Wooden block marked with a red percent sign on a tabletop.
Thinking About Waiting for Lower Mortgage Rates? Read This First.

October 4, 2026

Imagine waiting a year to buy a home, only to find mortgage rates haven’t changed much. That may sound frustrating.But it’s a real possibility.

Rolled U.S. hundred-dollar bills secured with yellow bands on a peach surface.
The Long-Term Cost of Renting vs. Buying

October 3, 2026

Real estate professional discusses documents with a client across a desk.
Here’s Where To Start if You’re Selling and Buying at the Same Time

October 2, 2026

If you’re a homeowner getting ready to move, one question usually comes first: should you buy your next home before you sell, or sell your current house before you sta… Read more

Aerial view of homes and parked cars along a tree-lined residential street.
What Higher Mortgage Rates Mean for Home Sellers

October 2, 2026

Higher mortgage rates don’t just affect buyers. They can change what it takes to sell your house, too. That’s because today’s buyers are paying close attention to aff… Read more

White-sided home entry with a charcoal paneled door, oak canopy, and brick-edged planting bed.
The Los Altos Farmers Market Has Two Closing Dates

October 1, 2026

A couple reviews paperwork with a real estate professional pointing to a document.
Hoping for (or Dreading) a Housing Crash? The Experts Just Weighed In.

October 1, 2026

Wooden percentage blocks beside miniature house tokens, illustrating real estate rates.
The Mortgage Rate You See Online Isn’t Necessarily the One You’d Get. FacebookTwitterPinterestLinkedIn You may have seen the headlines saying mortgage rates have climbed to the highest point since January 2025. And if that’s left you reluctant to buy a home, here’s what you need to remember… That’s not necessarily the number you’d get. It’s a common misconception that the rate you see in the headlines is the same one you’d get when you buy. The truth is, mortgage rates shift often, and the rate you actually end up with can vary a lot from what you may see or hear about. What Determines Your Real Rate? Advertised rates and “real rates” aren’t always the same. That’s because real rates are based on your specific situation, which includes your overall finances and goals. The rates you see in the headlines can’t possibly reflect that. That’s why only a lender can tell you what your real rate will be. To figure out your unique number, they’ll look at: Your credit score: Your credit score includes your payment history (if you’ve made late payments – and how often), credit utilization (are your accounts maxed out, or do you have available credit?), and the length of your credit history (how long have your accounts been open?). For example, someone with an exceptional credit score may qualify for a better rate. Your debt-to-income ratio (DTI): This is calculated by dividing your monthly debt payments by your monthly income before taxes to come up with a percentage. The higher your DTI, the higher your rate could be. The down payment size and Loan-to-Value (LTV): Your down payment is the percentage of the home’s price you will put down. The LTV is the percentage of a home’s sales price that equals your mortgage. The type and term of loan program options: Your loan officer will walk you through different loan options based on what you qualify for. Mortgage rates can vary between different loan products and programs. Even after you find a home you love, other things can have an impact too. For example: A mortgage rate buydown: This helps you get a lower mortgage rate, and by extension, a lower monthly payment, by paying an upfront cost. Sometimes a seller, builder, or another party may even offer to cover that cost themselves as an incentive for you to buy. Seller concessions: Sellers are allowed to pay buyer closing costs according to most loan program guidelines. Seller-paid closing costs can add up to thousands of dollars, which can free up some cash for you to increase your down payment, pay down debt, or make other financial adjustments to try to get a better rate. There’s a lot that can ultimately have an impact on your actual rate. Your First Step? Getting Pre-Approved. If you want to know if your number could be higher or lower than the headlines on social, you need to talk to an expert. A simple conversation with a loan officer can help you determine when you’ll be ready to buy, how much you can borrow, and of course, what your real rate will be. Your lender may recommend a pre-qualification and pre-approval: Pre-qualification is a general estimate of what you might be able to borrow based on self-reported information. On the flip side, pre-approval is actually a conditional commitment from a lender based on verified information. Just know that, of the two, the pre-approval process gives you a more accurate picture of your options than pre-qualification. Bankrate gives a quick comparison so you can see why: a blue and white chart with white text How To Get Ready for the Conversation Ask your lender what documents you’ll need to gather for that conversation. And keep these questions in your pocket too. They’re good things to go over when you talk: What will I gain or lose by waiting to buy a home for 3, 6, or 12 months? Will I get any tax advantages by buying a home – and what are they? What’s the benefit of buying a home and starting to build equity now versus waiting? And how does that impact my finances in the long run? How will rate changes in either direction affect me? Once you find out your rate, maybe you can buy now. Or maybe you still need to wait. But at least you’d know your options and can make an informed decision. Bottom Line Headlines and social media make today’s rates sound high. But you have to remember, the rate you’re seeing online and your actual rate could be different. The only way to know what your rate could be is to talk to a trusted lender. With the right help, you can find out what your real rate is – and where it can take you. Members: Sign in now to set up your Personalized Posts & start sharing today! Not a Member Yet? Click Here to learn more about KCM’s newest feature, Personalized Posts. « Why So Many Sellers Are Cutting Their Price Right Now September 28, 2026/by KCM CREW Language: English Español

September 30, 2026

You may have seen the headlines saying mortgage rates have climbed to the highest point since January 2025. And if that’s left you reluctant to buy a home, here’s what… Read more

Property Spotlight

Featured Video: Property Tour
Property Spotlight

Work With Us